
The short answer
Here is how to switch mortgage companies as a loan officer. Your current NMLS relationship ends. Your new company creates a relationship and requests sponsorship of your state licenses. You update and attest to your MU4. Your license status may be affected until the new sponsorship is in place, so plan the timing.
Before you resign, review your agreements. Ask how loans in process will be handled. Leave every borrower file with your current company.
This is general information, not legal advice. Check your agreements and talk to an attorney about your situation.
Before you give notice
Most problems in a move happen before the first NMLS click. Start here.
- Read your agreements. Look for non-solicitation, non-compete, confidentiality and notice clauses. Rules on these vary by state and by contract. If anything is unclear, talk to an employment attorney before you resign.
- Know your licenses. List every state where you hold a license. A company can only sponsor a license in a state where the company is also licensed or registered.
- Check the new company's state footprint. If it is not licensed where you are, it cannot sponsor you there.
- Ask about timing. Ask your new company how long sponsorship requests usually take with your states' regulators.
- Get your comp in writing. Get the offer and comp plan in writing before you resign.
Step-by-step: how to switch mortgage companies as a loan officer in NMLS
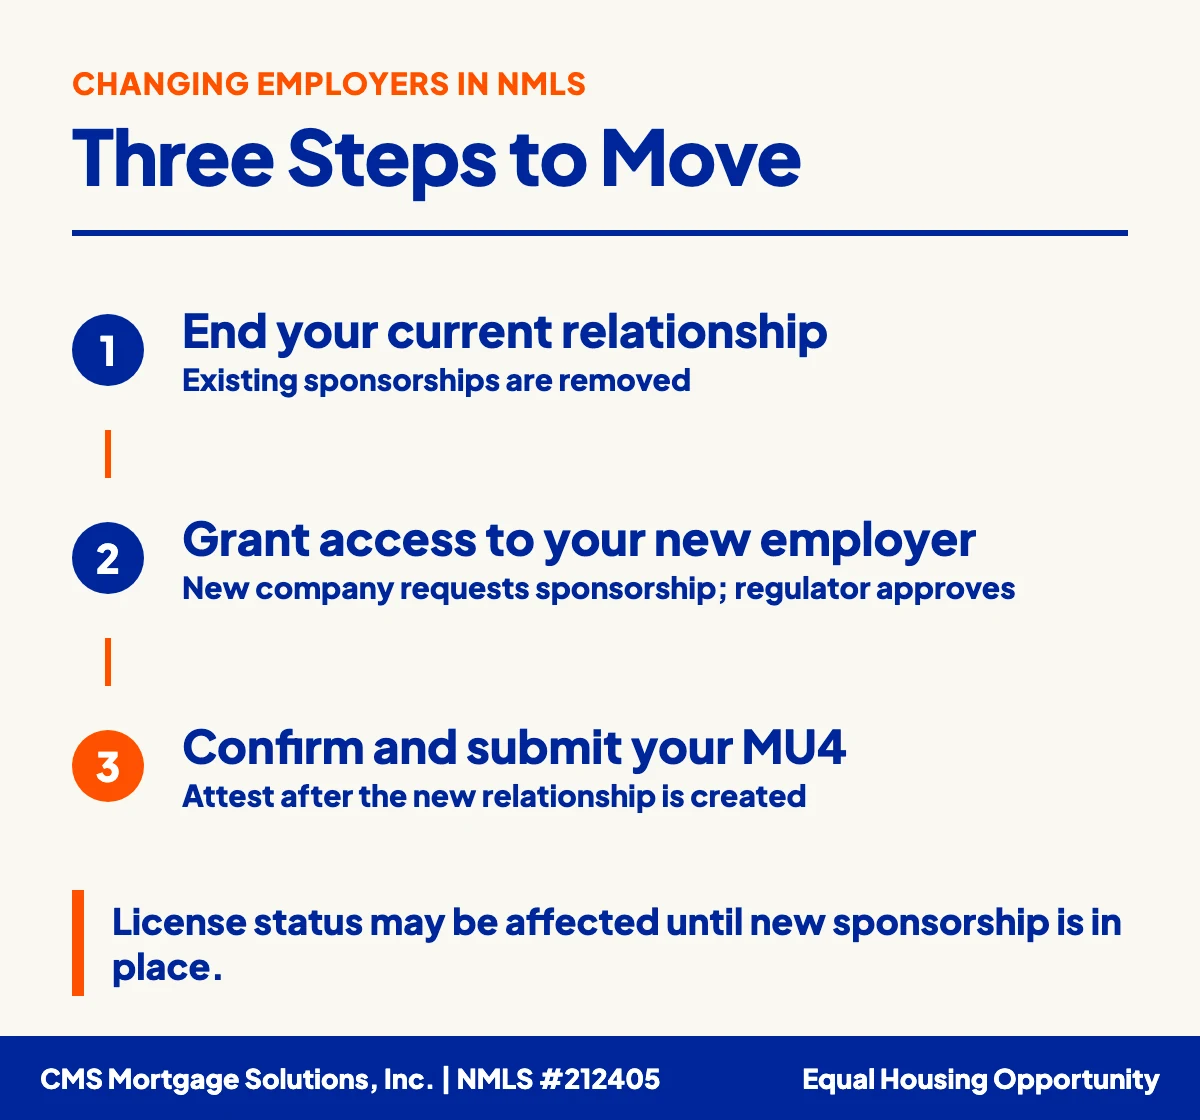
NMLS describes the employer change in three steps.
Step 1: End your current company relationship.
You or your current company can end the relationship in NMLS. You enter the end date in the Relationships & Sponsorships tab. Ending the relationship removes your existing sponsorships. NMLS notes that your license status may be affected until your new employer submits a sponsorship request. NMLS also says sponsorships and sponsorship removals are reviewed by the regulator.
Step 2: Grant access to your new employer.
You give your new employer access to your NMLS record. Your new employer then creates a relationship with you and submits a sponsorship request for your licenses. Only a company can start a sponsorship. The state regulator must approve it.
Step 3: Confirm your changes and submit your MU4.
After your employer creates the relationship, NMLS emails you to review and submit your MU4. Confirm your contact details and employment history. Then complete the MU4 amendment attestation.
Also check your state's amendment checklist in the NMLS State Licensing Checklist Compiler. NMLS tells you to review it for requirements outside NMLS.
Sponsorship can carry an NMLS processing fee and state agency fees. NMLS says a first-time sponsorship carries no charge, but a sponsorship after a job change may not count as first-time. Ask your new company what applies to you and who pays.
Temporary authority: when it applies
Federal law gives some loan originators temporary authority to originate while a license application is pending. Under the SAFE Act, as amended in 2018, it covers two groups:
- Registered loan originators moving from a bank or credit union to a state-licensed mortgage company. They must have been registered in NMLS as an MLO during the one-year period before they apply.
- State-licensed loan originators seeking a license in another state. They must have been licensed as an MLO in a state other than the new one during the 30 days before they apply.
Both groups must work for a state-licensed mortgage company in the state where they apply. NMLS reads "employed" as a W-2 employee, not a 1099 contractor. The company must also have requested sponsorship.
You do not qualify if you have:
- Had an MLO license application denied, or an MLO license revoked or suspended, in any jurisdiction
- Been subject to or served with a cease and desist order
- Been convicted of a misdemeanor or felony that would preclude licensure under the law of the state where you apply
Temporary authority starts when you submit the license application with the required background check information. It ends at the earliest of these:
- You withdraw the application
- The state denies the application or issues a notice of intent to deny it
- The state grants the license
- 120 days pass after you submit, if NMLS lists the application as incomplete
What about a move between two state-licensed companies in a state where you are already licensed? The NMLS temporary authority FAQ describes the two groups above. It does not address that move. In that case your license is already issued, so the usual path is sponsorship by your new company. Do not assume temporary authority applies. Ask your state regulator or the NMLS Call Center before you take applications.
Your pipeline checklist
Your pipeline is the hardest part of a move. Handle it carefully. This section is general information. Your agreements and your state's rules control.
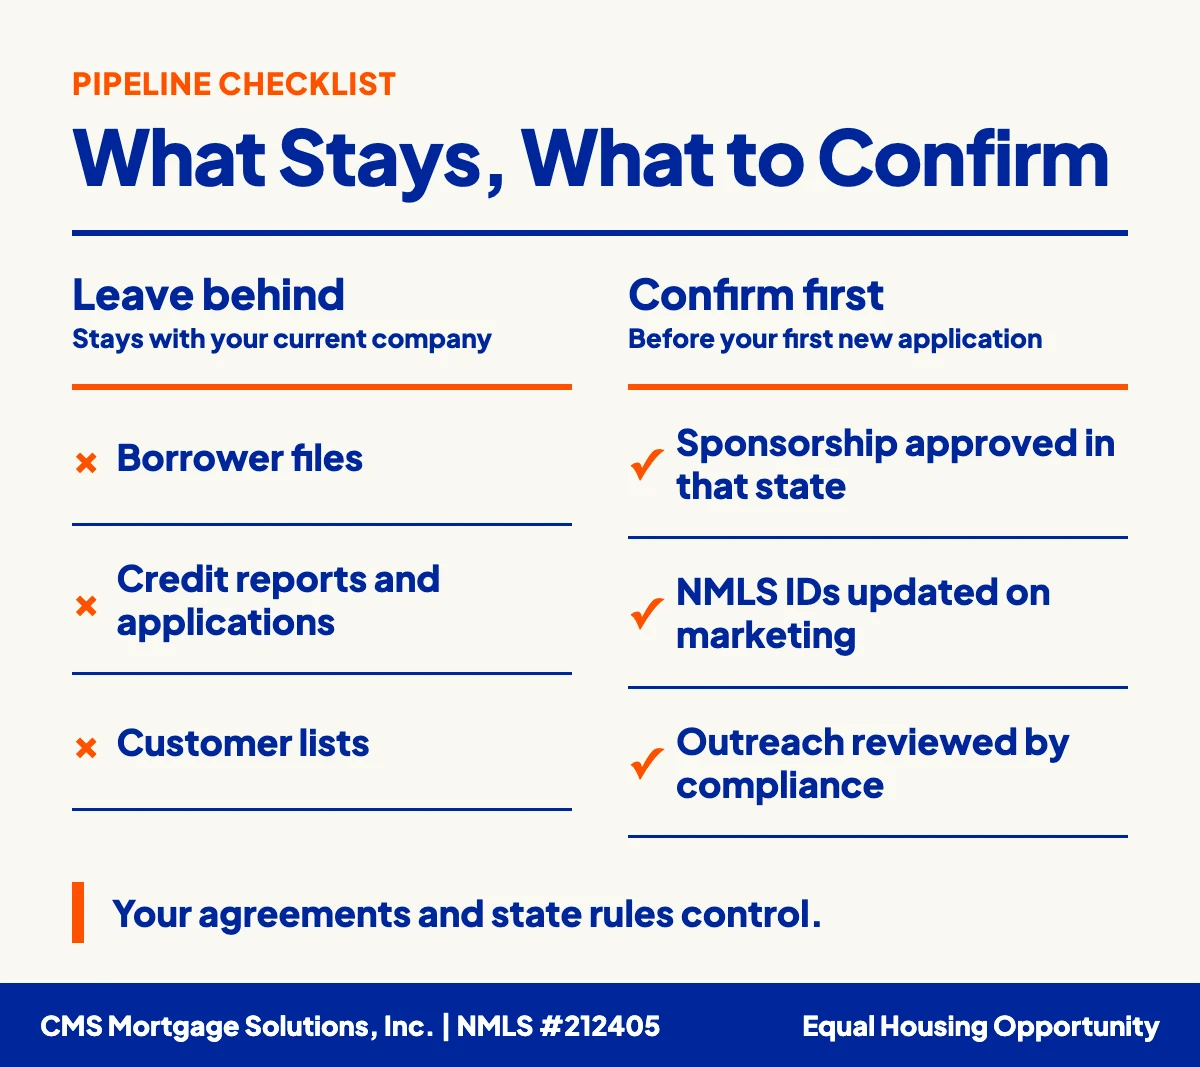
- Ask what happens to loans in process. Applications taken under your current company are generally handled by that company. Your agreements and lender relationships decide the details. Plan the handoff with your manager.
- Do not take borrower files. Do not download, forward, print or copy borrower files, credit reports, applications or customer lists. Federal law requires financial institutions to protect the privacy and security of customers' nonpublic personal information. Your company's policies likely go further. Leave it all behind.
- Do not move loans yourself. Do not transfer, re-submit or redirect a borrower's application to your new company on your own. Follow your agreement and the law.
- Do not originate where you are not sponsored. Federal law says you may not act as a loan originator without the required license or registration and a unique identifier. In most states NMLS says sponsorship is also required to originate under a company license. Do not take applications for your new company in a state until sponsorship there is approved. Do not rely on temporary authority unless your new company confirms you are eligible for it.
- Update your marketing. Keep your NMLS ID and your company's name and NMLS number accurate on websites, social profiles, email signatures and business cards. Federal Regulation Z requires the loan originator organization's and individual's names and NMLS IDs on certain loan documents, such as the application, the note and the security instrument. State advertising rules vary. Have your new company's compliance team review your materials.
- Talk to your referral partners carefully. Check your agreements before you contact anyone. Terms on non-solicitation and on use of contacts can limit what you say and to whom. Ask an attorney, and ask your new company's compliance team, what you may say before you reach out.
Common mistakes
- Resigning before confirming the new company is licensed in all your states
- Taking client lists or borrower files "just for reference"
- Taking an application before your sponsorship is approved
- Forgetting to update the NMLS ID on your website and social profiles
- Missing the MU4 attestation after the new relationship is created
How CMS approaches it
If you are weighing a move, compare the whole operating setup, not just the split. CMS's for loan officers page describes a tiered comp plan that moves with production, a playbook library, Bright Processing working your conditions and leadership you can reach directly. You can also read side-by-side comparisons, such as CMS vs. NEXA and CMS vs. EDGE.
FAQ
Do I need a new NMLS license when I switch companies?
Generally not in states where you are already licensed. Your new company requests sponsorship of your existing license, and the regulator approves it. Your new company must be licensed in each of those states.
Who ends my NMLS relationship?
You or your current company can end it. Ending it removes your sponsorships.
Can I originate loans while my sponsorship is pending?
Ask your new company and your state regulator before you take any application. Your license status may be affected until sponsorship is approved. Temporary authority applies only in specific cases.
Can I bring my pipeline with me?
Loans in process are generally handled by your current company, and borrower files stay there too. Review your agreement and get legal advice if you are unsure.
What is the MU4?
It is your individual NMLS filing. You update and attest to it after your new employer creates a relationship with you.
How long does a transfer take?
It depends on your states and how quickly sponsorship requests are approved. Ask your new company what to expect.
Sources
- NMLS Resource Center, Changing Employers
- NMLS Resource Center, Getting Sponsored by Your Employer
- NMLS Policy Guide, Sponsoring a License
- NMLS Resource Center, Creating Relationships and Requesting Sponsorships
- NMLS Policy Guide, Temporary Authority eligibility requirements and Temporary Authority FAQs
- 12 U.S.C. 5117, Employment transition of loan originators, and 12 U.S.C. 5103, License or registration required
- Public Law 115-174, Sec. 106
- 12 CFR 1026.36(g), NMLSR ID on loan documents
- 15 U.S.C. 6801, Protection of nonpublic personal information
Ready for a confidential conversation?
If you are a licensed loan officer thinking about your next move, see if CMS is a fit, explore the loan officer model or view careers. Conversations are confidential.
---
This content is for educational purposes and does not constitute legal or compliance advice. Licensing requirements vary by state. Consult NMLS, your state regulator and an attorney about your situation.
CMS Mortgage Solutions, Inc. | NMLS #212405 | Virginia Beach, VA. Equal Housing Opportunity. NMLS Consumer Access.